Algorithmic Spotting of Irregular Patterns in Vendor Mobile Bank Movements
Payment anomalies in mobile bank transfers surface when transaction patterns deviate from established norms for a given vendor account, and researchers have documented these deviations through volume spikes, unusual timing, or mismatched recipient details. Machine learning systems process large datasets of historical transfers to establish baseline behaviors, then flag outliers in real time before funds move through clearing networks. Data from payment processors shows that anomaly rates in mobile-initiated bank transfers rose notably between 2024 and 2025, prompting vendors to adopt automated detection layers that operate without manual review for every entry.
Core Mechanisms Behind Pattern Recognition
Supervised learning models train on labeled examples of confirmed fraud cases alongside legitimate transfers, while unsupervised approaches cluster transactions to isolate those that fall outside normal groupings. Experts note that random forest and gradient boosting techniques often combine multiple variables such as device location, transfer amount relative to past averages, and frequency within a 24-hour window to generate risk scores. These scores determine whether a transfer proceeds, triggers additional verification, or routes to a review queue, and financial institutions report processing millions of such evaluations daily with minimal latency.
One study released in early 2026 by academic teams at the University of Toronto examined over 12 million mobile ACH-style transfers and found that ensemble models reduced false positives by 34 percent compared with rule-based systems alone. The same analysis indicated that models incorporating geolocation and behavioral biometrics maintained accuracy even when vendors operated across multiple time zones.
Integration Points in Mobile Transfer Workflows
Vendors typically initiate bank transfers through mobile applications that connect directly to automated clearing systems, and machine learning sits between the app interface and the backend authorization step. Real-time scoring occurs within milliseconds, allowing the system to pause or approve the request before it reaches the network. Observers have recorded that banks in the European Union began requiring such detection layers for high-volume merchant accounts starting in late 2025, aligning with updated directives on electronic payments.
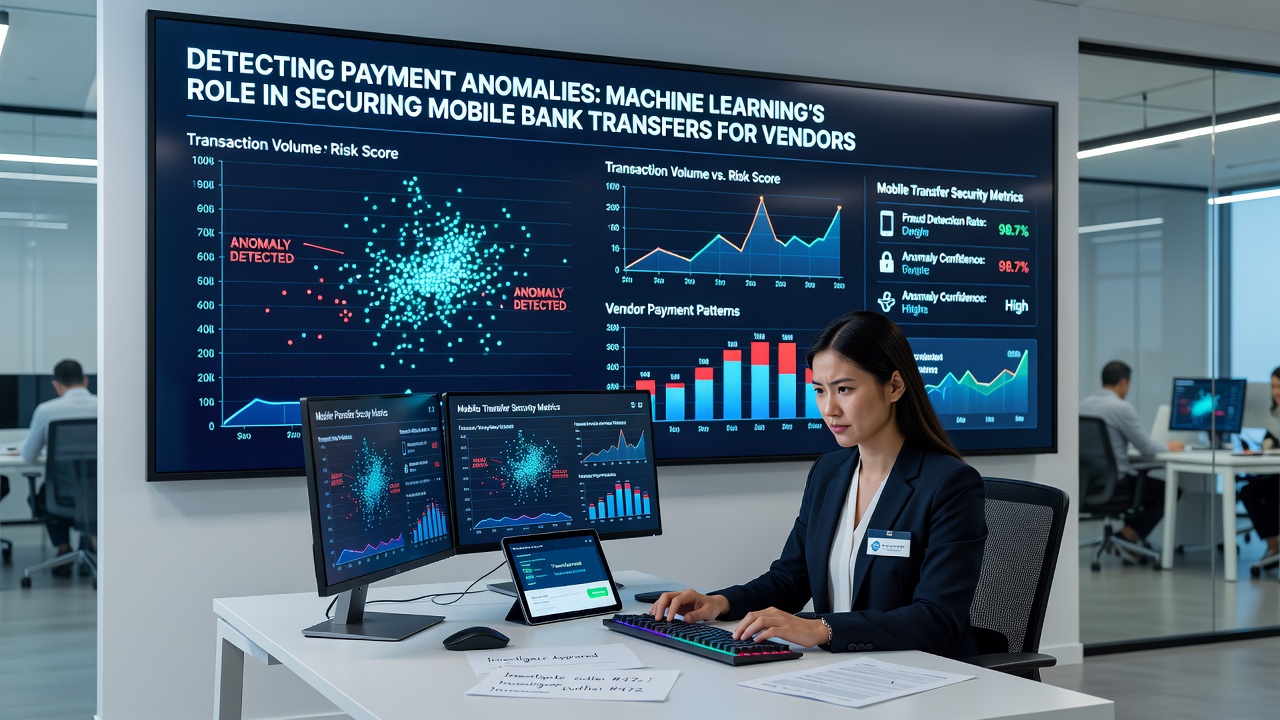
Continuous learning pipelines update model weights as new transaction data arrives, which helps systems adapt to seasonal shifts such as increased end-of-quarter payments common among vendors. Researchers at the Reserve Bank of Australia published findings in September 2026 showing that retraining intervals of two weeks kept detection rates above 91 percent for anomalies involving cross-border mobile transfers. Those figures came from a controlled dataset spanning 18 months of merchant activity.
Case Examples from Industry Deployments
Take one logistics vendor that processes daily payouts to independent drivers through mobile bank transfers, where an ML system flagged a cluster of payments sent to accounts never previously used by the same device. The pattern triggered a secondary authentication step that prevented unauthorized movement of funds exceeding $180,000 across a single weekend. Similar deployments in retail supply chains have caught attempts to alter beneficiary details mid-session by comparing current requests against stored vendor profiles.
Another documented instance involved a wholesale supplier whose mobile app recorded a sudden increase in small-value test transfers followed by larger ones, a sequence often associated with account takeover attempts. The detection engine combined velocity checks with network analysis of the originating IP addresses and halted the sequence before settlement occurred. Figures released by the Bank for International Settlements indicate that organizations using these layered approaches saw a 27 percent drop in successful unauthorized transfers during the first half of 2026.
Data Sources and Regulatory Context
Regulatory bodies such as the Federal Reserve have issued guidance encouraging machine learning adoption for real-time monitoring of faster payment rails that include mobile bank transfers. In parallel, the Monetary Authority of Singapore released updated risk-management expectations in mid-2026 that reference anomaly detection as a core control for non-bank payment service providers. Academic papers indexed on platforms like arXiv continue to explore graph neural networks that map relationships between multiple vendor accounts to surface coordinated fraud rings operating across devices.
Conclusion
Machine learning continues to refine its capacity to isolate irregular mobile bank transfers before they reach clearing stages, drawing on expanding datasets and evolving model architectures. Vendors gain operational continuity when detection systems operate transparently in the background, and the documented reductions in loss events across multiple jurisdictions demonstrate measurable impact from these technologies. Ongoing research and regulatory updates ensure that detection capabilities keep pace with shifting tactics observed in electronic payment environments.